

This article offers general educational information about real estate valuation, not legal, financial, or appraisal advice. Consult a licensed attorney, appraiser, or advisor about your specific situation.
Ever wondered why one home sells fast while a pricier, near-identical one sits for months?
The answer is a simple rule called the principle of substitution. It shapes how homes get valued, how loans get approved, and how tax and legal disputes get settled.
If you are a lawyer, a law student, or an advisor who wants a clear grasp of this idea, you are in the right place.
This guide keeps things plain. You will get the definition, the law behind it, how appraisers use it, a real example with numbers, and its limits.
What the Principle of Substitution Actually Means
The principle of substitution says a buyer will not pay more for a property than the cost of getting an equally desirable substitute.This assumes there is no major delay in making the swap.
It works two ways. Comparable homes set the top limit on value. And when two homes are alike, demand moves to the cheaper one.
"Equally desirable" does not mean identical. The substitute only needs similar utility, appeal, and highest and best use.
Highest and best use is a quick test worth knowing. It asks what use of a property is legal, possible, and brings the most value. Two homes are true substitutes only when they share the same best use.
A house and a corner lot zoned for shops are not real substitutes, even if they sit side by side.
Where the Principle of Substitution Fits in Property Law
Property value is not a guess. It rests on set economic rules that courts, lenders, and tax offices accept, and substitution is one of them.
It links to the legal meaning of market value used in mortgage lending: the most probable price a property should bring in a fair, open market. Both the buyer and seller act with knowledge and in their own best interest.
This standard, known asfair market value, appears in federal lending rules and in USPAP, the rulebook appraisers follow.
Why This Principle Matters for Legal and Financial Decisions
This principle shapes real money decisions and legal outcomes. It shows up in three places advisors meet often: loan appraisals, tax appeals, and contract disputes. Here is how it counts in each.
Loan Appraisals and Lending Disputes
Lenders use appraisals to set loan amounts. Those appraisals lean on comparable sales, often called comps, which come straight from substitution.
If an appraisal comes in low, the loan may shrink or fall through.
The gap between a low appraisal and the agreed price is called the appraisal gap. When this happens, the buyer can pay the difference, walk away, or ask for a reconsideration of value.
A reconsideration asks the appraiser to review fresh comps that may have been missed. Advisors who grasp how comps drive value can spot weak reports and question them.
Property Tax Assessments and Appeals
Assessors value homes using comparable sales and cost data. Comparable sales show what similar homes sold for. Cost data shows what it would take to rebuild the home today, minus wear and tear.
When an owner feels their assessment is too high, this principle becomes the base of the appeal. You show that similar homes carry lower values. A strong comparable set is often the heart of a winning tax challenge.
Contracts and Fair Market Value Claims
Fair market value sits inside many contracts and disputes. Substitution helps prove whether a price truly reflects the market.
If a buyer paid far above comparable homes, one side may argue the price was not fair. Clear comparable evidence can support or defeat these claims and cut down on costly legal fights.
How Appraisers Apply the Principle in Real Estate Appraisal
Substitution is not one method. It is the logic that sits under the three main appraisal approaches. Agents use the same logic in a Comparative Market Analysis, or CMA, when they price a home against similar ones nearby.
Here is a quick look at how the three approaches compare:
| Approach | What it values | How substitution applies |
| Sales Comparison | Homes with recent nearby sales | Buyer pays no more than a like home that sold |
| Cost | New or special-use buildings | Buyer pays no more than the cost to build an equal one |
| Income | Rental and investment property | Investor pays no more for the same income stream |
The Sales Comparison Approach
This approach sets value by comparing the home to similar ones that were recently sold. A careful buyer pays no more than the price of a comparable, equally desirable home.
Appraisers adjust for differences like size or condition. Here is how an adjustment works. Say a comp sold for $340,000 but has a finished basement the subject home lacks.
The appraiser subtracts the basement's value, maybe $10,000, to make a fair match. If the comp is worse than the subject, they add value instead. The comparable needing the fewest adjustments carries the most weight.
The Cost Approach
Here, value equals land plus the depreciated cost of the building. The logic is simple.A buyer will not pay more for a home than the cost to build an equally desirable one.
Appraisers often use replacement cost, which builds a home of equal use with today's materials, rather than an exact copy of the old structure. This approach works best for new or one-of-a-kind buildings where few sales exist.
The Income Approach
This approach fits rental and investment property. It values a home on the income it can produce. A tenant or investor picks the property that gives the same return or use for less money.
To turn income into value, appraisers often use a gross rent multiplier or a capitalization rate. They may divide a property's price by its yearly income to find a rate. Then they apply that rate to similar properties to estimate what the subject is worth.
A Real Example of the Principle of Substitution in Action
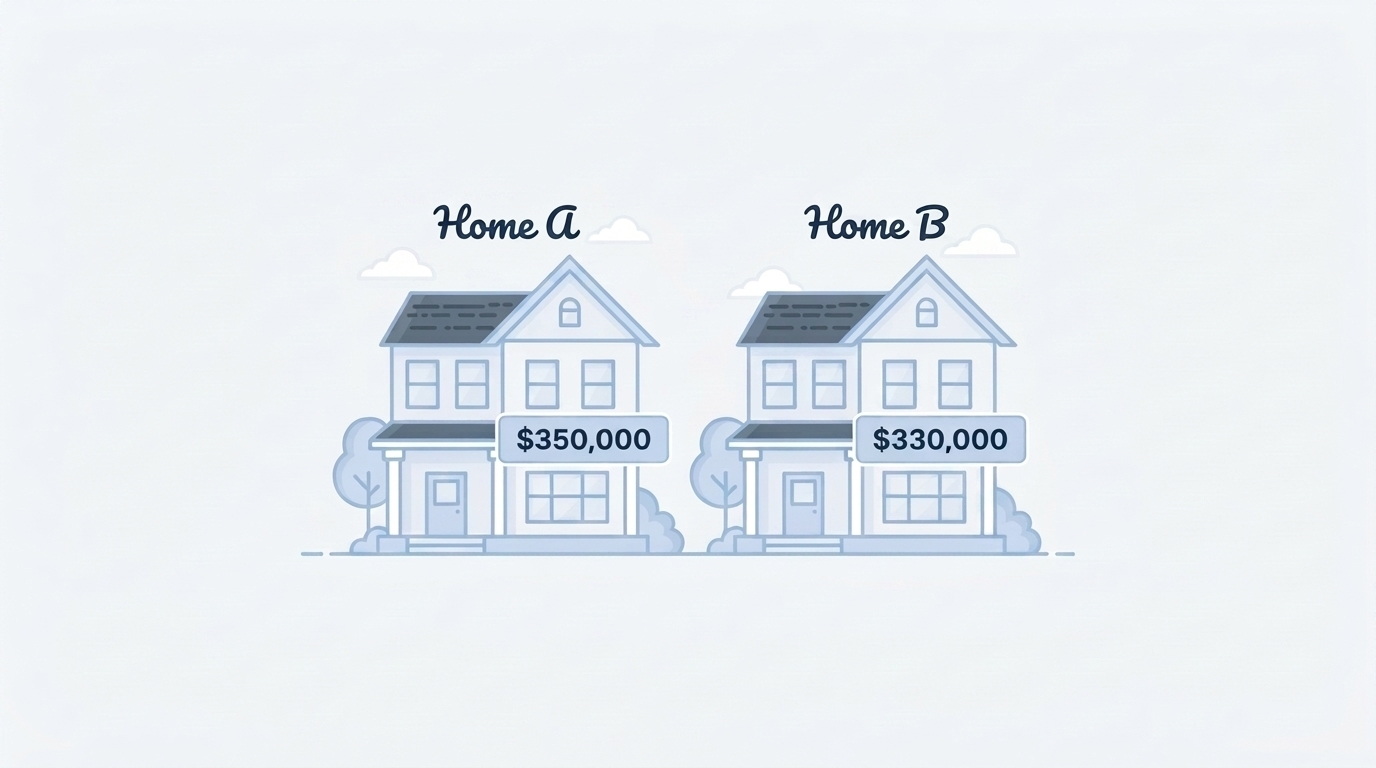
Think about two homes on the same street. Both have three beds, two baths, and the same square footage. Home A is listed at $350,000. Home B is listed at $330,000.
With all else equal, most buyers pick Home B. The lower price pulls demand. Home B also sets the value ceiling, since few will pay more for a similar home.
One caution. A single high sale, called an outlier, is rarely the best sign of market value. This is why appraisers use several comparables, not one.
Low inventory can also push buyers to overpay. This is supply and demand at work. That does not change the principle.
As appraiser Jamie Owen of the Cleveland Appraisal Blog notes, the priciest home among similar ones is the least likely to sell when a buyer can get a similar home for less.
Limits and Exceptions Every Advisor Should Know
The principle holds in most cases, but a few situations can weaken it.
These are the main limits to flag before relying on any valuation:
- One-of-a-kind properties: A home with no true match, like a historic estate or a special-purpose site, does not follow the principle well. There is no comparable substitute to set its value.
- Fast or shaky markets: In volatile markets, prices shift quickly. Substitutes become hard to predict, and comparable sales may already be out of date.
- Subjective comparisons: No two properties are exactly alike. Adjusting for size, condition, or features involves judgment, which can lead to varied value opinions.
- Old or thin data: The principle needs current market data to work. When recent sales are few or the numbers are stale, the value can slip and become harder to defend.
Conclusion
Here is the one thing to remember: a buyer will not pay more when a similar home costs less. Keep that rule close, and you will read valuations with sharper eyes.
Found this helpful? Share it with a colleague or drop a comment below with your own take.
Frequently Asked Questions
Who first came up with the principle of substitution?
The idea grew from early economic thinkers and is now core to appraisal texts like The Appraisal of Real Estate. It has guided value theory for generations.
Is the principle of substitution the same as the law of one price?
They are close cousins but not the same. The law of one price applies to identical goods, while substitution works with similar, not identical, properties.
Does the principle of substitution apply to vacant land?
Yes. A buyer compares similar lots and picks the lower-priced one with equal use. Location and zoning drive which lots count as true substitutes.
How does the principle of substitution differ from the principle of conformity?
Substitution sets value by comparing prices of like homes. Conformity says a home holds more value when it matches the style of nearby homes.
Can the principle of substitution affect a home appraisal for divorce or estate cases?
Yes. Appraisers use comparable sales to set a fair value in divorce, probate, and estate splits. This keeps the division honest and defensible.