

If you've typed what is real estate frauds into a search bar, something probably made you uneasy. Maybe a wiring email looked off, or a rental seemed too cheap.
Property deals move big money. One wrong click can cost you a down payment or even your home.
This guide explains what real estate fraud means and how the main scams work. You'll see wire fraud, deed fraud, mortgage fraud, rescue scams, and rental scams.
You'll also learn what doesn't count as fraud and which warning signs mean you should pause. By the end, you'll know how to catch a scheme before money leaves your hands.
These examples follow patterns reported by the FBI and state legal aid groups.
Disclaimer: This guide shares general information, not legal advice. Laws vary by state, so check with a licensed attorney about your situation.
What Is Real Estate Fraud?
Real estate fraud happens when someone lies, hides facts, or uses fake documents to trick a buyer, seller, renter, or lender into giving up money or property.
It can involve a stranger posing as a landlord, a seller hiding known damage, or a scammer forging ownership papers.
The goal is always the same: get money or property through deception. Fraud can target anyone, from first-time renters to experienced investors.
How Real Estate Fraud Works
Most real estate scams follow a simple pattern. A scammer creates a believable story, such as a too-good-to-be-true rental price or a property "for sale by owner" that needs a quick wire transfer.
They build trust fast, often avoiding phone calls or in-person meetings. Then they create urgency, pushing the victim to send money before they have time to verify details.
Once the payment clears, the scammer disappears, and the property either does not exist or was never theirs to sell or rent.
The FBI's Internet Crime Complaint Center logged about $275 million in real estate losses in 2025, up 58% from 2024.
What Are the Main Types of Real Estate Fraud?
Real estate frauds fall into two broad groups. Some target the people in a deal, while others target the lender funding the loan.
Wire Fraud
Wire fraud usually strikes days before closing. A scammer hacks or copies the email of your agent, lawyer, or title company.
Then you get a message with "updated" wiring instructions. Security experts call this business email compromise. The scammer has usually been reading the email thread, so the timing feels right.
You send your down payment, and it lands in the scammer's account instead. That money often moves again within hours, which makes recovery hard.
A real title company won't mind if you call to confirm the numbers.
Title and Deed Fraud
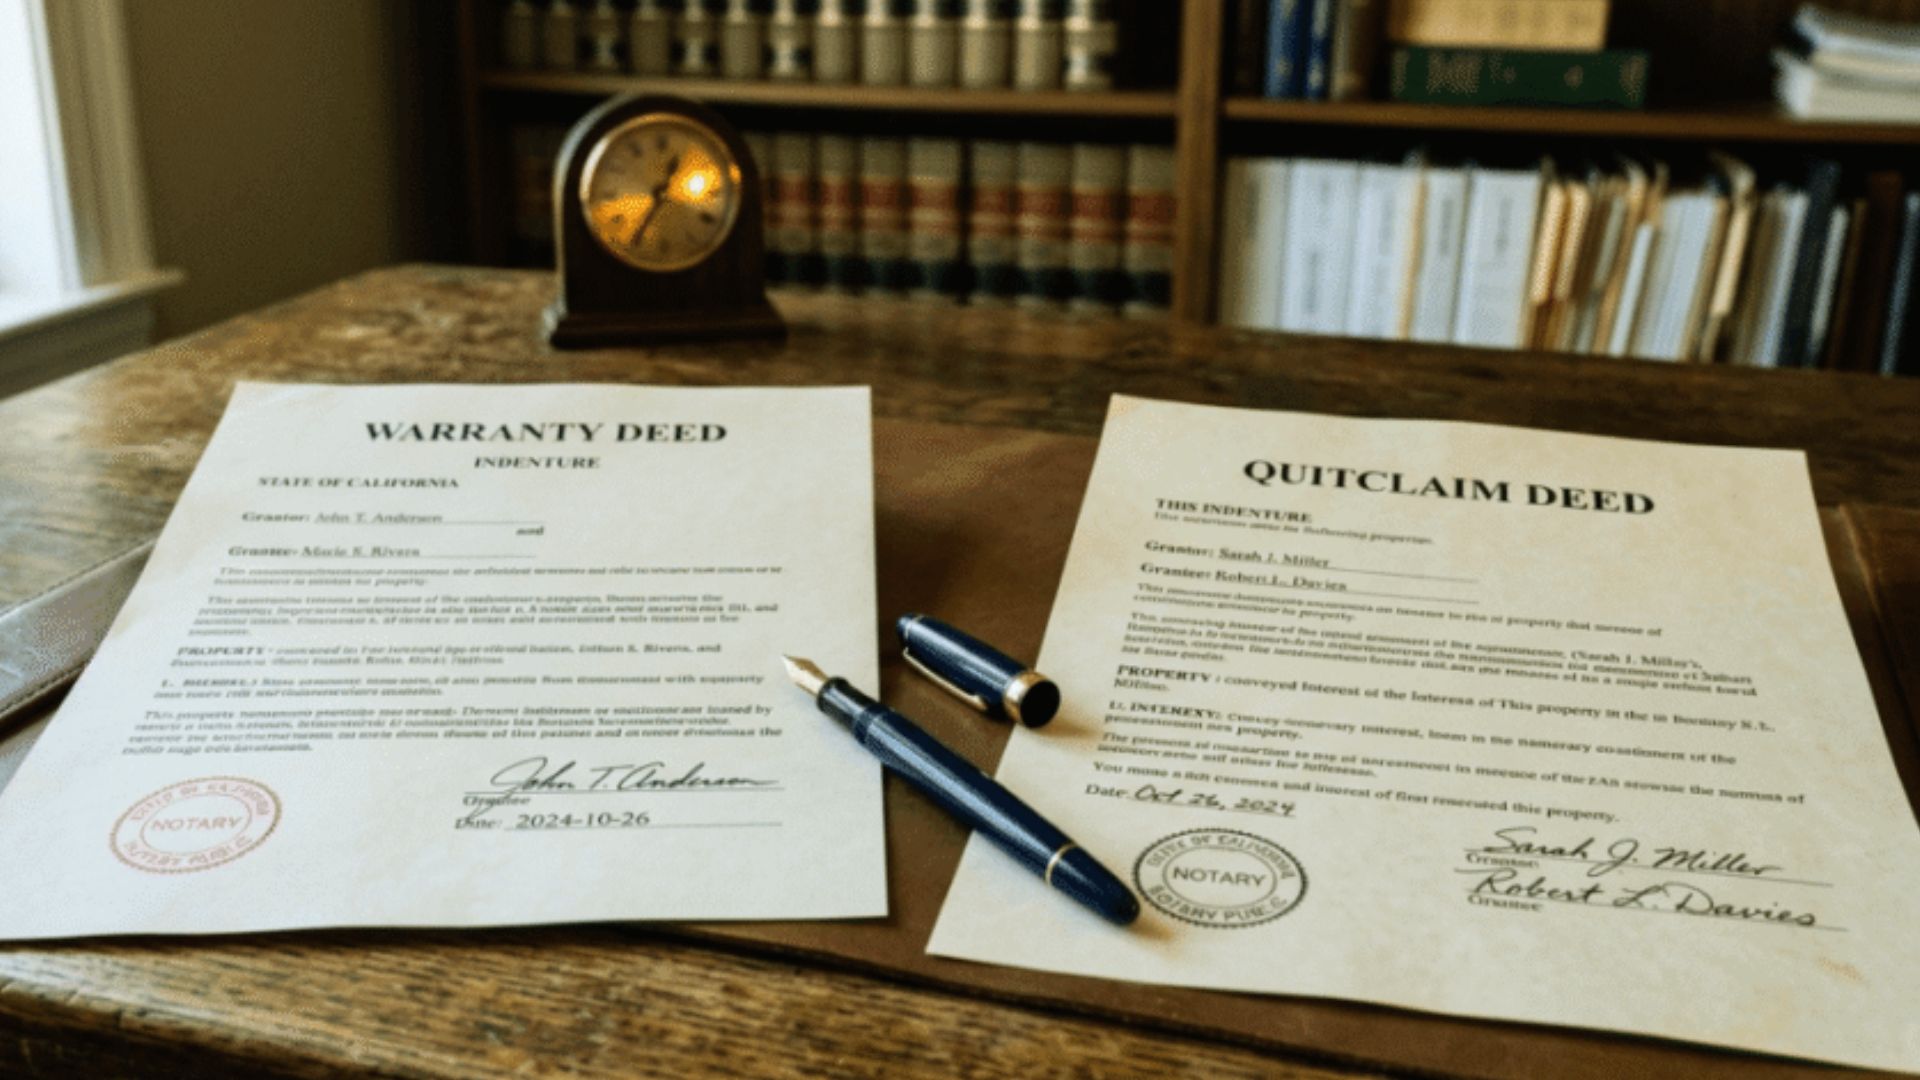
Deed fraud happens when a criminal forges your signature or poses as you to sign your property away. The fake deed puts the home in their name, and they sell it or borrow against it.
Most owners assume the government would catch a fake deed. It usually doesn't.
The county recorder files any deed that looks complete, meaning signed, notarized, and paid for. Clerks generally don't check whether the signer truly owns the home.
So a forged deed with a fake notary stamp can land on the public record like a real one.
That gap is what makes seller impersonation work. Scammers pick vacant land, rentals, or paid-off homes with no lender watching.
They list the property with a real agent, push for a fast cash sale, and sign everything remotely.
Mortgage Fraud
Mortgage fraud flips the usual story. The victim is usually the lender, and the person lying is often the borrower.
The simplest version is fraud for housing. A buyer fakes pay stubs, hides debts, or lies about living in the home to get a loan.
Many borrowers see it as a small fib to get a home. It can still be a federal crime.
Fraud for profit is bigger and more organized. It often involves insiders like appraisers, brokers, or loan officers working together.
Common setups include inflated appraisals, straw buyers who lend their name and credit, and illegal flipping at fake high prices. The group pulls cash out of the loans, then lets the homes fall into foreclosure.
Foreclosure Rescue Scams
Foreclosure rescue scams go after owners who are behind on payments and scared of losing their home. Real options exist, though, and some owners can still sell a house in foreclosure before the auction. Scammers copy those promises to look legitimate.
Some "rescuers" charge a large upfront fee and then disappear. Federal rules generally bar mortgage relief companies from collecting fees before they deliver results. Some " rescuers " charge large upfront fees and then disappear.
Others ask you to sign the deed over so you can rent and buy it back later. Once they hold title, your equity and your home are gone.
Rental Scams
Rental scams use listings for homes the scammer doesn't own. They often copy photos from a real sale listing and post a rent far below market.
The "landlord" is always traveling or too busy to show the inside. They ask for a deposit and first month's rent by wire, gift card, or payment app.
When you show up, someone else lives there, or the real owner has never heard of you.
What Does Not Count as Real Estate Fraud?
Real estate fraud needs intent. Losing money in a property deal doesn't make it fraud on its own. The same goes for vague sales hype, known as puffing in real estate.
Overpaying for a house isn't fraud. Neither is a surprise repair bill, a low appraisal, or a buyer backing out.
Seller disclosures are where it gets gray. A seller who truly didn't know about a leaky basement made a mistake, not a crime.
A seller who painted over water stains to hide that leak is a different story. Depending on your state's disclosure laws, that can be fraud or misrepresentation.
Not every fraud case is criminal, either. Many disputes are civil, meaning you sue for money instead of calling the police.
That difference determines whether you call a lawyer or law enforcement first.
Who Gets Targeted and What Are the Warning Signs?
Scammers pick targets that match the scheme. Owners of vacant land and paid-off homes draw deed fraud, since no lender watches their title.
Homeowners behind on payments draw rescue scams. First-time buyers and older adults are frequent wire fraud targets around closing.
Whatever your role, the warning signs tend to repeat. Stop and check the deal if you notice any of these:
- A request to wire money that you haven't confirmed by phone, using a number you already trust
- A seller or landlord who won't meet in person or let you see inside
- Offers that sound too good, like guaranteed quick profit or instant debt relief
- Pressure to sign blank or rushed paperwork
One red flag doesn't prove fraud, but it's reason enough to pause. Nothing should get signed or wired until it checks out.
How Can You Prevent Real Estate Fraud?
Most schemes fall apart when someone slows down and checks. A few habits close the common gaps before any money moves.
Use a licensed escrow or title company, and look up their license with your state. Confirm wiring instructions by phone, using a number from your signed contract.
Buy an owner's title insurance policy. It can cover losses tied to forged documents in a property's past. Ask your county recorder if it offers free alerts for any filing under your name.
Meet sellers and landlords in person or on live video, then match their ID to the public owner record. Never pay with gift cards, cash, or payment apps.
If someone pushes back on any of these steps, treat that as your answer. A real seller, landlord, or agent will wait.
Final Takeaway
So, what is real estate frauds in plain terms? It's any deal where someone lies on purpose to take your money, your home, or a loan.
The tricks vary, yet most lean on speed and secrecy. Scammers need you rushed and alone.
Take your time on every step. Call a known number, read each page, and ask questions until the answers make sense. Honest people in a deal rarely mind a little extra checking.
Frequently Asked Questions
Is real estate fraud a crime?
Yes. Most forms of real estate fraud are crimes under state law, and many are federal crimes too. Mortgage fraud and wire fraud often get charged as bank fraud, wire fraud, or mail fraud. Penalties depend on the scheme and the loss, but they can include prison time, fines, and paying the victims back.
Where do you report real estate fraud?
Start with your local police and get a report number. For wire fraud, file a complaint with the FBI's Internet Crime Complaint Center at ic3.gov. Mortgage fraud tips can go to the FBI or your state attorney general. If a fake deed was filed, tell your county recorder's office too.
Can you get your house back after deed fraud?
In most cases, yes. A forged deed usually carries no legal power, so the real owner still holds title. But fixing the public record takes a court case, often called a quiet title action. A real estate attorney handles this. If you have owner's title insurance, call the insurer early, since it may cover the costs.
What should you do if you wired money to a scammer?
Call your bank right away and ask them to recall the wire. Speed matters most here, because the money often moves again within hours or days. Then file a report at ic3.gov and with local police. Also tell your title company or agent so they can warn others in the deal.