Many people feel confused when they hear the phrase "irrevocable trust." Who actually owns the property once it's inside one? That's one of the most common questions people ask when planning their estate.
This article breaks down exactly who owns the property in an irrevocable trust, how ownership shifts after the transfer, and what rights each party holds.
You will also learn how it compares to a revocable trust and what mistakes to avoid. Understanding this can help you protect your assets and plan smarter for the future.
Working with estate planning concepts like this one does not have to feel overwhelming when explained clearly, and having the right information makes all the difference when making big financial decisions.
What Is an Irrevocable Trust
An irrevocable trust is a legal arrangement where you transfer assets into a trust you generally cannot change or take back once it is created.
Picture this: you sign a legal document, hand over control of your assets, and walk away knowing they are protected under a structure you set up in advance.
That is exactly how an irrevocable trust works. You, the grantor or settlor, create the trust, name a trustee to manage it, and choose beneficiaries to receive the benefits.
Once the assets are transferred, the trustee takes full control and must follow the trust document at all times. The trust becomes its own separate legal entity, distinct from you and everyone else involved.
People choose this path for many solid reasons, including protecting assets from creditors, cutting down estate taxes, qualifying for Medicaid, and passing property to children or grandchildren in a controlled and intentional way.
Who Owns the Property in an Irrevocable Trust
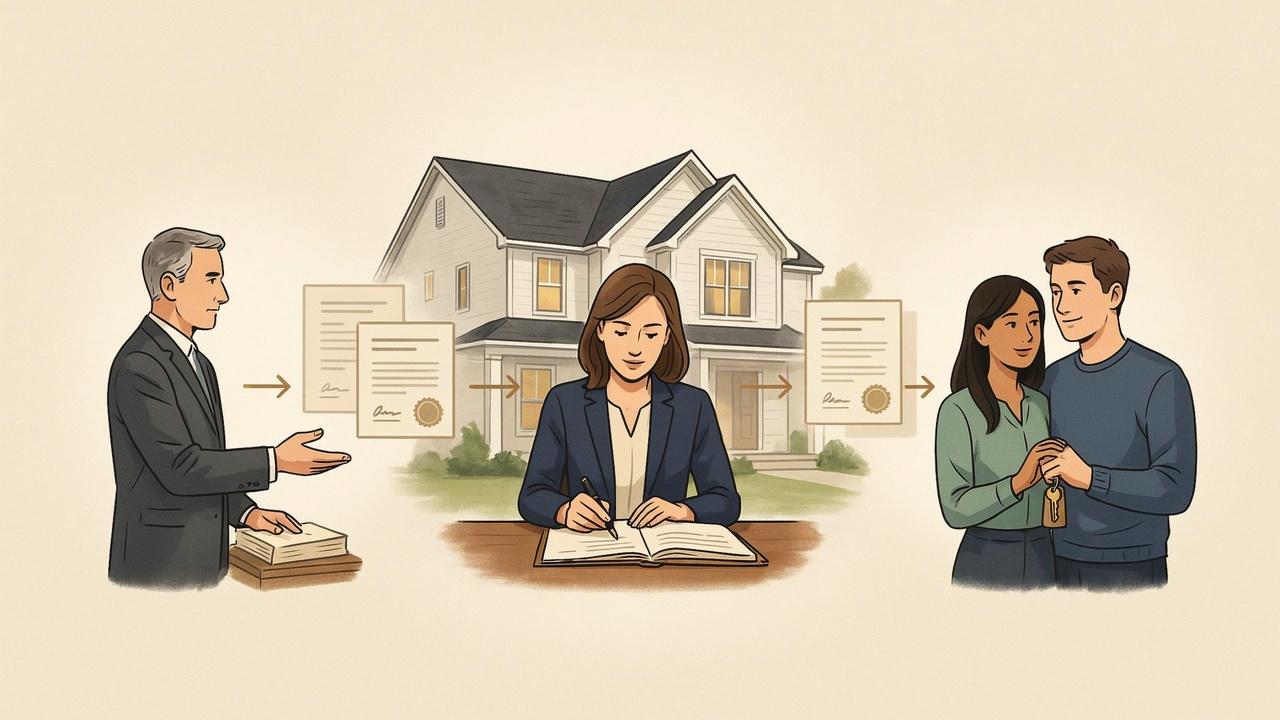
When property goes into an irrevocable trust, ownership is split across different roles, and each role carries specific rights and limits.
Who Holds Legal Title
The trustee holds legal title to the property. This means the trustee's name appears on deeds and documents. But holding legal title does not mean the trustee can use the property for personal gain.
The trustee manages the property strictly for the benefit of the beneficiaries. Think of it like being a manager of someone else's property. You are in charge but the property is not yours to keep.
What Rights the Grantor Keeps
Once you transfer property into an irrevocable trust, you give up most of your rights to it. You cannot take it back, sell it on your own, or change the trust terms without the beneficiaries' consent.
In some states, you might retain limited rights depending on how the trust is structured. But in most cases, the grantor steps away from control completely.
That loss of control is actually what makes the trust effective for asset protection and tax planning.
What Authority the Trustee Has
The trustee has the legal power to manage, invest, and distribute trust assets.
This includes paying bills related to trust property, filing taxes for the trust, selling assets if the trust document allows it, and distributing income or principal to beneficiaries.
However, the trustee cannot act outside the terms of the trust. Every action must line up with what the trust document says.
Trustees also have a fiduciary duty, meaning they must act in the best interest of the beneficiaries at all times. If a trustee misuses trust assets, they can be held personally responsible.
What Beneficiaries Actually Own
Beneficiaries hold what is called a beneficial interest. They do not own the property outright, but they have the right to benefit from it.
This could mean receiving income from a rental property inside the trust, living in a home the trust owns, or inheriting assets when the time comes.
Beneficiaries may also have the right to request an accounting from the trustee to see how funds are being managed.
The nature of the beneficiary's interest depends on how the trust is written. Some trusts give beneficiaries immediate income rights while others hold everything until a future date.
How Property Ownership Changes in a Trust
Once property enters an irrevocable trust, the rules around it shift significantly. Understanding these changes helps you avoid surprises later.
What Happens After Property Is Transferred
After the transfer, the property legally belongs to the trust as a separate legal entity. The grantor's name is removed from the title.
The trustee steps in as the legal owner on paper. For real estate, a new deed is recorded showing the trust as the owner.
For financial accounts, the account is retitled in the name of the trust. These steps are not optional. Skipping them means the transfer is incomplete and the asset may not be protected.
Can the Property Be Sold or Refinanced
Yes, trust property can be sold or refinanced, but only if the trust document allows it and only by the trustee. The trustee must exercise those powers responsibly and in the beneficiaries' best interests.
If the trust permits a sale, the trustee handles it and the proceeds stay inside the trust. The grantor cannot independently decide to sell the property.
Some trusts include specific rules about when or how property can be sold, and those rules must be followed strictly.
What Happens After the Grantor Dies
When the grantor passes away, the trust continues to operate. A successor trustee named in the trust document may step in to manage the process if needed.
The trustee manages and distributes assets according to the trust's instructions. Because the assets are not part of the grantor's personal estate, they typically avoid probate.
This is one of the biggest benefits. The property can pass to beneficiaries faster and with more privacy than going through a court process.
Estate taxes may also be reduced depending on how the trust was structured.
Can Property Be Removed From the Trust
In most cases, no. That is the defining feature of an irrevocable trust. Once assets are inside, they stay there unless the trust document specifically allows removal or all beneficiaries agree to changes under state law.
Some states allow a process called decanting, where assets move from one trust to another with updated terms. But this is not always available and usually requires legal help.
Never assume you can take property back out without checking the trust document and your state laws.
Revocable vs Irrevocable Trust
Both trust types are useful, but they serve very different purposes. Knowing the difference helps you choose the right tool for your situation.
| Feature | Revocable Trust | Irrevocable Trust |
| Ownership and Control | The grantor keeps full control and can change, revoke, or add assets to the trust at any time. The property is still considered the grantor's for legal and tax purposes. | The grantor gives up ownership and control after transferring the property. The trust becomes the legal owner, and changes are generally limited. |
| Asset Protection | Offers little or no protection from creditors because the grantor still owns the assets. | Provides stronger asset protection since the assets are no longer legally owned by the grantor and are generally beyond the reach of creditors. |
| Tax and Estate Planning | Trust assets remain part of the grantor's taxable estate and do not reduce estate taxes. | Properly structured trusts can remove assets from the taxable estate, reduce estate taxes, and support gifting strategies. An irrevocable life insurance trust, for example, keeps life insurance proceeds out of the taxable estate entirely. |
| Which Trust Is Better for Your Goals | Best for people who want flexibility, control, and a simple way to avoid probate while managing their estate. | Best for those seeking asset protection, Medicaid planning, estate tax reduction, or long-term wealth preservation, even if it means giving up control of the assets. |
Should You Choose a Revocable or Irrevocable Trust?
Both revocable and irrevocable trusts help manage and transfer assets, but they serve different purposes. The right choice depends on your goals, the control you want to keep, and the level of asset protection you need.
When Each Trust Makes Sense
A revocable trust is a good choice if you want to maintain control over your assets during your lifetime. You can change the terms, add or remove property, or even cancel the trust if your circumstances change.
It is commonly used to avoid probate, simplify estate administration, and provide a plan if you become unable to manage your affairs.
An irrevocable trust is better suited for people who want stronger asset protection or estate tax planning.
Once assets are transferred, you generally give up control, but those assets may receive protection from creditors, reduce estate taxes, and support long-term planning goals such as Medicaid eligibility or preserving wealth for future generations.
Which Trust Is Better for Different Situations
There is no single trust that works best for everyone. The right choice depends on what you want to accomplish.
- Choose a revocable trust if your priority is flexibility, maintaining control, and avoiding probate.
- Choose an irrevocable trust if your goal is protecting assets, reducing estate taxes, planning for Medicaid, or creating a lasting financial legacy.
- Talk with an estate planning attorney if your situation involves business ownership, significant assets, blended families, or special tax considerations. Professional guidance can help ensure the trust matches your long-term objectives.
Mistakes to Avoid When Transferring Property
People make costly errors when setting up irrevocable trusts. Here are the most common ones and how to avoid them.
Confusing Ownership With Control
Many grantors think that because the trustee manages the property, the grantor still has some form of ownership. That is not true.
Once the transfer is complete, the grantor's rights are gone. Trying to act like you still own the property can create legal and tax problems.
Understand clearly that you are giving up ownership in exchange for the trust's protections.
Failing to Transfer Assets Properly
Creating the trust document is just step one. You must actually re-title the assets in the name of the trust. Many people sign the trust and think the job is done.
But if the deed still shows your name or the bank account is not retitled, those assets are not protected.
Work with your attorney and financial institutions to make sure every asset is properly transferred.
Choosing the Wrong Trust Type
Not every irrevocable trust works the same way. A Medicaid asset protection trust works differently than a charitable remainder trust or a special needs trust.
Choosing the wrong type means you may not get the benefits you expected. Be clear about your goals before picking a trust type.
Your attorney should explain the options and help you pick the one that matches your needs.
Ignoring State Trust Laws
Trust laws vary by state. Some states allow more flexibility in modifying irrevocable trusts, including the option of trust decanting.
Others have strict rules about what a trustee can and cannot do. If you move to a different state after creating the trust, the rules may change.
Always work with an attorney who knows your state's laws and review the trust if you relocate.
Tips Before Putting Property in a Trust
Before you sign anything, take time to plan carefully. These steps can save you time, money, and legal trouble.
- The trustee carries serious responsibility, so choose someone honest, financially knowledgeable, and capable of handling family disagreements without bias. Name a successor trustee in the document as a backup in case your first choice is unable to serve.
- Match the trust structure to your long-term goals, whether that is protecting assets, planning for a special needs child, or reducing estate taxes.
- Keep clear and updated records of everything inside the trust, including deeds, account statements, and insurance policies.
- Transferring property can trigger gift taxes or affect Medicaid eligibility, so always review the timing and legal implications with a professional first.
- What seems like a smart move today can carry hidden costs tomorrow, so never skip the legal and financial review before making any decisions.
Conclusion
Understanding who owns the property in an irrevocable trust can feel complex at first, but it gets clearer once you know the roles involved.
The trustee holds legal title, beneficiaries hold beneficial interest, and the grantor steps back from control.
The trust itself operates as a separate legal entity, and that separation is what makes it powerful for asset protection and estate planning.
Now that you know how it works, take the next step and speak with an estate planning attorney.
If this article helped you, feel free to share it with someone who might benefit or leave a comment below with your questions.
Frequently Asked Questions
Can a Beneficiary Also Serve as a Trustee in an Irrevocable Trust
Yes, a beneficiary can serve as a trustee, but this can create conflicts of interest and potential tax issues depending on the powers granted.
Does Property in an Irrevocable Trust Affect Credit Score
No, placing property in an irrevocable trust does not directly impact your personal credit score since ownership transfers away from you.
What Happens if the Trustee of an Irrevocable Trust Dies
A successor trustee named in the trust document steps in. If none is named, a court may appoint one to continue managing the trust.
Can an Irrevocable Trust Own a Business or Rental Property
Yes, an irrevocable trust can hold business interests or rental properties, with the trustee managing them according to the trust document's instructions.
Is Income Generated by Trust Property Taxable
Yes, income generated by irrevocable trust assets is generally taxable, either to the trust itself or to beneficiaries depending on distributions made.