

You’ve signed the trust. Then you look at your mortgage statement and wonder if the bank can demand the whole loan back.
It usually can’t. The part that trips people up comes later, in the paperwork nobody reminds them to finish.
I’ve watched families find the gap years after the transfer. The deed was right, but the insurance, title, or county filing wasn’t.
That’s the real work behind putting a house in trust with a mortgage. The loan is rarely the issue. The loose ends are.
You’ll see what keeps your loan safe, what can quietly break, and how to finish every step properly.
Disclaimer: This article is general information, not legal advice. Check your state’s rules with a licensed attorney before transferring your home.
Can You Put a House in a Trust if It Still Has a Mortgage?
Yes. The federal Garn-St Germain Act of 1982 protects you, and you won’t need to refinance.
It applies if you stay a beneficiary, keep living in the home, and the property has fewer than five units.
Only the deed moves into the trust. The loan stays in your name. So the lender doesn’t need to approve anything, and your monthly payment stays exactly the same.
Most mortgages contain a due-on-sale clause. It lets the lender demand the full balance if you transfer the home to someone else.
A deed moving into a trust can look like that kind of transfer. Garn-St Germain stops the lender from using the clause in this case.
This protection has limits, though. Rentals, second homes, and irrevocable trusts don’t qualify. In those cases, your lender keeps the right to call the full loan due.
Why Put a House With a Mortgage in a Trust?
The biggest reason is probate. A house held in a trust usually passes to your heirs without going through court.
That saves time, and it can save real money. A trust also protects you if you can’t manage your own affairs.
Your successor trustee steps in and keeps the mortgage paid, with no court appointment needed. Probate files are public record. A trust stays private.
What Do You Need Before Moving a Mortgaged House Into a Trust?
Two things come first: a signed trust and your current deed. The trust’s exact name, date and trustee must match the new deed word for word.
Gather these papers before you start. Having them ready keeps the transfer from stalling halfway.
- Current deed: Copy the legal description from it exactly.
- Mortgage statement: Use the latest one, since it shows your loan number.
- Owner’s title policy: Keep it close in case coverage questions come up.
- Insurance declarations page: Your homeowners insurer will need to add the trust.
Every owner on title must sign, too. That includes joint owners and spouses in community property states.
How Do You Put a House With a Mortgage Into a Trust?
Sign the trust, prepare the new deed, sign and record it, confirm recording, update insurance and title, notify your servicer.
Each step depends on the one before it. The last three are the ones people skip most.
Step 1: Sign Your Revocable Living Trust
A deed can’t name a trust that doesn’t legally exist yet. So the trust gets signed first, before any property paperwork. Sign it in front of a notary. Some states also require witnesses.
Name a successor trustee in the document. That’s the person who takes over if you die or can’t manage your affairs.
Pick someone organized, reliable and willing to handle paperwork. Name a backup in case your first choice can’t serve.
Store the signed original somewhere safe and fireproof. Tell your successor trustee where it is.
Step 2: Prepare the New Deed
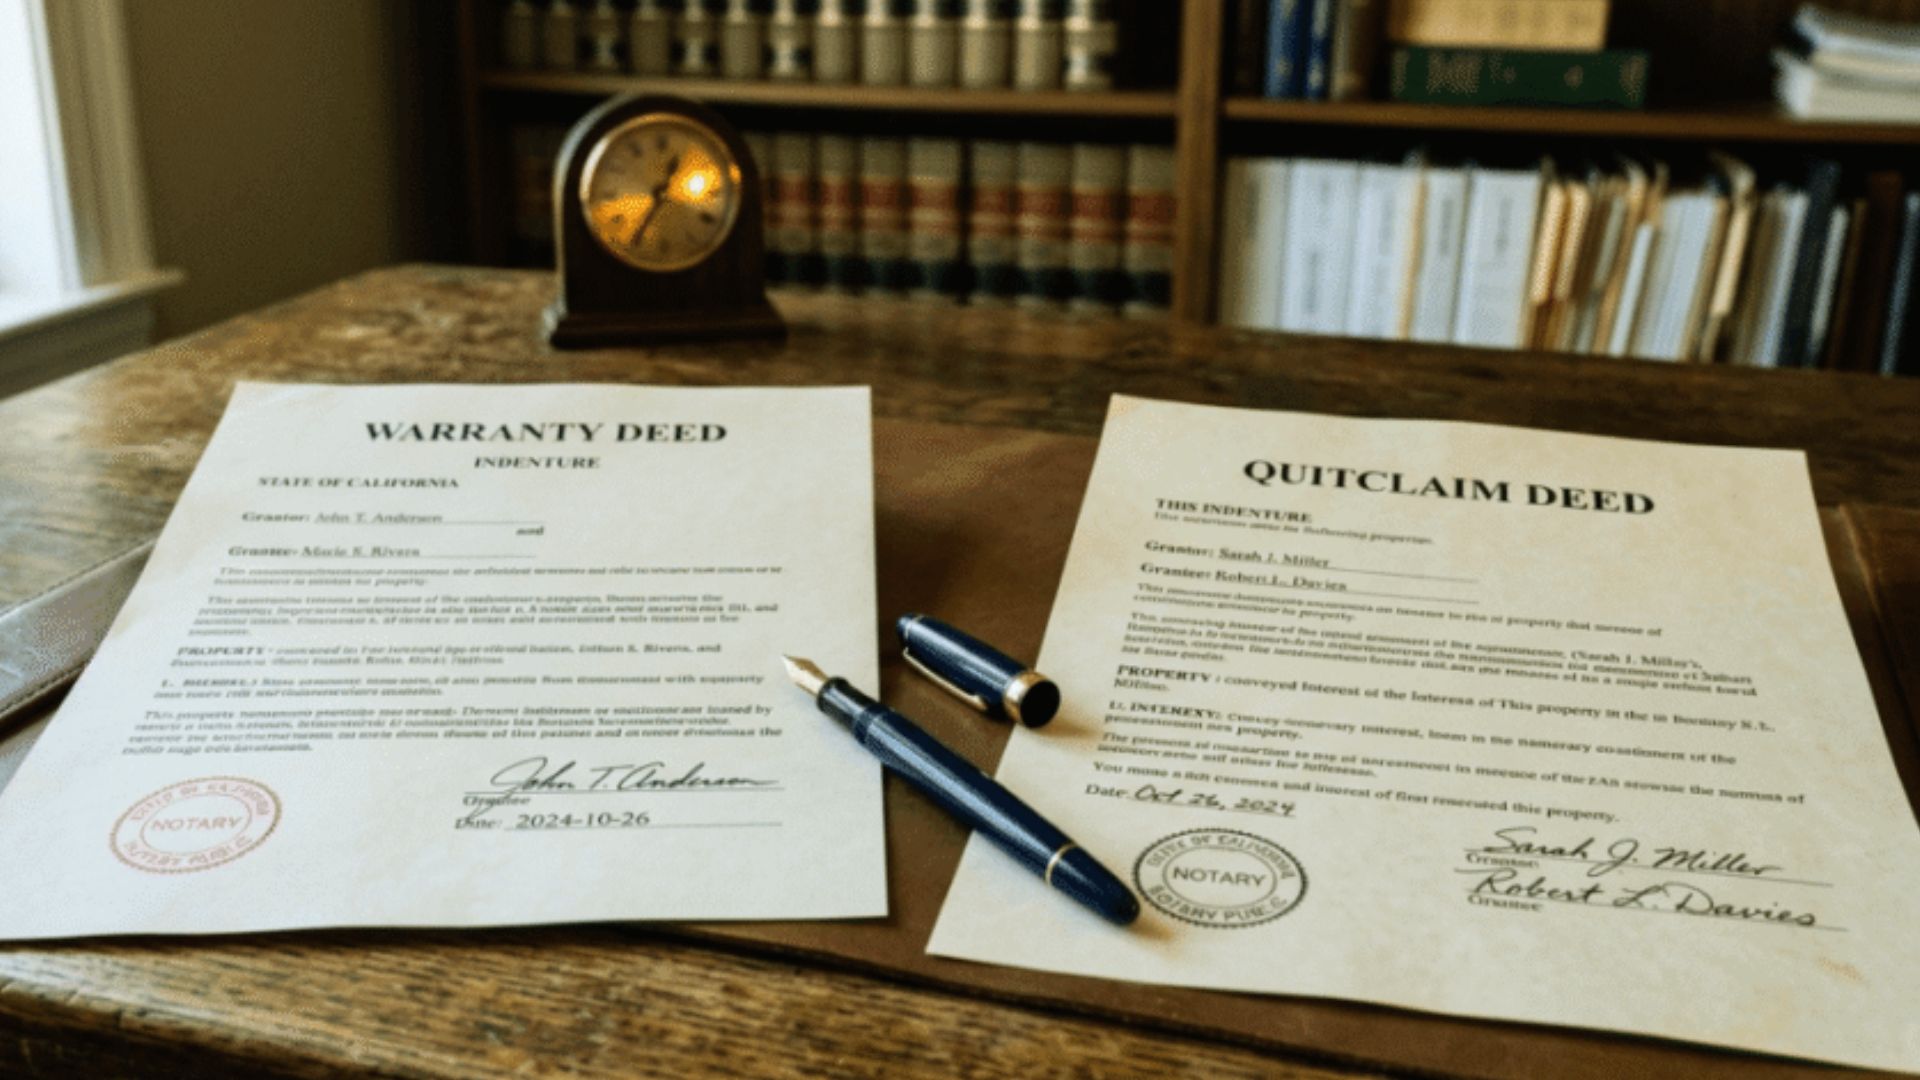
This step changes the most from state to state. Some states use a grant deed. Others use a warranty or quitclaim deed.
Many states also require a transfer form, even when no transfer tax is owed.
Copy the legal description from your current deed exactly. One wrong lot number or boundary line can cloud the title.
The new owner must be written exactly as your trust reads.
For example: “Jane Doe, Trustee of the Jane Doe Revocable Trust dated [date].”
Step 3: Sign, Notarize, and Record the Deed
Sign the new deed in front of a notary. Every owner on the title needs to sign, including spouses in community property states.
Then take or mail the deed to your county recorder’s office. Expect a recording fee. It usually runs between $25 and $100 for a standard deed, though county schedules vary and some charge more.
If your state offers a transfer tax exemption, attach that form now. A missing form can delay or block recording.
Some counties also want a cover sheet or specific page margins. Check their website before you submit. Keep a copy of everything you send, including the check or payment receipt.
Step 4: Confirm the Deed Was Recorded
Filing the deed doesn’t mean it’s done. The county still has to process and record it. That can take a few days or several weeks.
Watch your mail for the stamped copy they send back. The stamp shows the recording date and document number. That’s your proof.
No copy after a few weeks? Search your county’s online records by your name or parcel number.
The listing should show the trust as owner and a recording date. If it doesn’t, call the recorder’s office. Store the stamped deed with your trust papers.
Step 5: Update Your Homeowners Insurance and Title Policy
Call your insurer and ask them to add the trust as an additional insured. Without this, the insurer can argue the trust isn’t covered. A claim for a fire or burst pipe could then be delayed or denied.
Ask for an updated declarations page that lists the trust. Keep it with your records. The title policy gets forgotten most. Your owner’s policy was issued to you personally, not the trust.
Ask your title company if you need an endorsement to keep coverage in place. Some policies carry over automatically. Others don’t.
Either way, get the answer in writing. Do this right after recording, not years later.
Step 6: Notify Your Mortgage Servicer
Send your servicer a short written notice about the transfer. Include your loan number and a copy of the recorded deed.
Your loan terms, rate, and monthly payment stay the same. You keep making the payments yourself, just as before.
Send the letter by certified mail with a return receipt. Save that receipt, since it proves they were told.
Some servicers send forms asking about the trust or your occupancy. Answer promptly and keep copies. If they mention calling the loan, point them to the Garn-St Germain Act.
What Are the Downsides of Putting a Mortgaged House in a Trust?
The built-in trade-offs are upfront cost and extra paperwork. The bigger risks come from choosing the wrong trust type or missing a state filing. Title gaps are the third risk, and they stay hidden for years.
Using an Irrevocable Trust
An irrevocable trust means giving up control. You usually can’t change it or take the house back on your own.
The federal protection likely no longer applies either. Your lender could call the loan, so get written consent first.
This route needs an attorney who handles both the trust and the loan.
Missing Property Tax or Homestead Filings
Most states don’t reassess property tax when a house moves into a revocable trust. The catch is the homestead exemption.
Some states or counties want a new filing after the transfer. Miss it, and the exemption can drop off your next tax bill.
Rules differ a lot by state. Call your county assessor before recording the deed.
Leaving Title Insurance Behind
Some older owner’s title policies only cover you personally. Once the title moves to the trust, that coverage can quietly end.
You won’t notice at the transfer. The problem shows up years later, when a sale uncovers an old lien or boundary issue.
Ask your title company to confirm your coverage in writing now.
Can I Put My House in a Trust to Avoid Creditors?
Not with a revocable trust. You keep full control and can take the house back anytime, so courts treat it as yours.
Your mortgage lender never goes away either. Its lien moves into the trust right along with the title.
Irrevocable trusts and certain state asset protection trusts can shield a home. But timing matters.
If you move the house to dodge debts you already owe, courts can undo the transfer. Voidable transfer laws exist for exactly that.
The Bottom Line
A mortgage doesn’t stop your house from going into a trust. Skipped paperwork does. That’s the real lesson behind how to put a house in a trust with a mortgage.
The deed, the recording, the insurance, the title and the servicer each need a finish line. Miss one, and the gap waits for your family to find it.
If this helped, share it with someone planning their estate this year.
Frequently Asked Questions
Who Pays the Mortgage if the Trust Owner Dies?
The loan doesn’t end at death. Your successor trustee keeps paying from trust funds. If a relative inherits and moves in, federal law generally stops the lender from calling the loan.
Can You Sell a House That’s in a Trust?
Yes. The trustee signs the sale paperwork, and the title company will ask for a certificate of trust. Your mortgage gets paid off at closing, like any sale.
Does Putting Your House in a Trust Affect Your Credit?
No. The loan stays in your name, so your payment history reports the same way. Only missed payments or new debt change your score, and the transfer causes neither.
Do You Need a Lawyer to Put Your House in a Trust?
Most states don’t require one. But a small deed mistake can cause title problems years later. With multiple owners or out-of-state property, a professional review is worth paying for.
What Happens if You Forget to Move the House Into the Trust?
The trust only controls what it owns. A house left in your name may go through costly probate after you die. Checking your recorded deed now avoids that.