

Adding your name to a deed feels simple. Sign here, and now you both own the place.
But owning property as a joint tenant with rights of survivorship comes with rules that usually surface only when something goes wrong.
Maybe a co-owner’s debts show up at your door. Maybe you realize your will can’t touch a share you thought was yours to leave behind.
I’ve seen families assume this setup protects them, only to find out later what it actually controls and what it doesn’t. This isn’t about scaring you off it.
It’s about knowing exactly what you’re signing, what it costs to undo, and what it means for taxes, control, and the people you’d want to inherit from you.
What Joint Tenancy With Rights of Survivorship Means?
Joint tenancy with rights of survivorship means two or more people own the same asset together. Each person holds an equal, undivided interest in the whole thing.
Nobody owns a specific slice. If three siblings hold a house this way, none of them owns “a third of the kitchen” or “the back bedroom.”
Each owner has a claim to the entire property, not a fenced-off piece of it. That’s what “undivided” means.
Tenants in common share the whole property too, but their shares can be unequal, like 70/30, and each share passes through the owner’s will. Joint tenants always hold equal shares, and those shares never pass through anyone’s will.
There’s one more piece that makes this structure what it is. When one owner dies, their interest doesn’t pass down through a will or through probate court.
It moves automatically to the surviving owners. That single fact shapes almost everything else about how this type of ownership works.
How the Right of Survivorship Actually Transfers Property
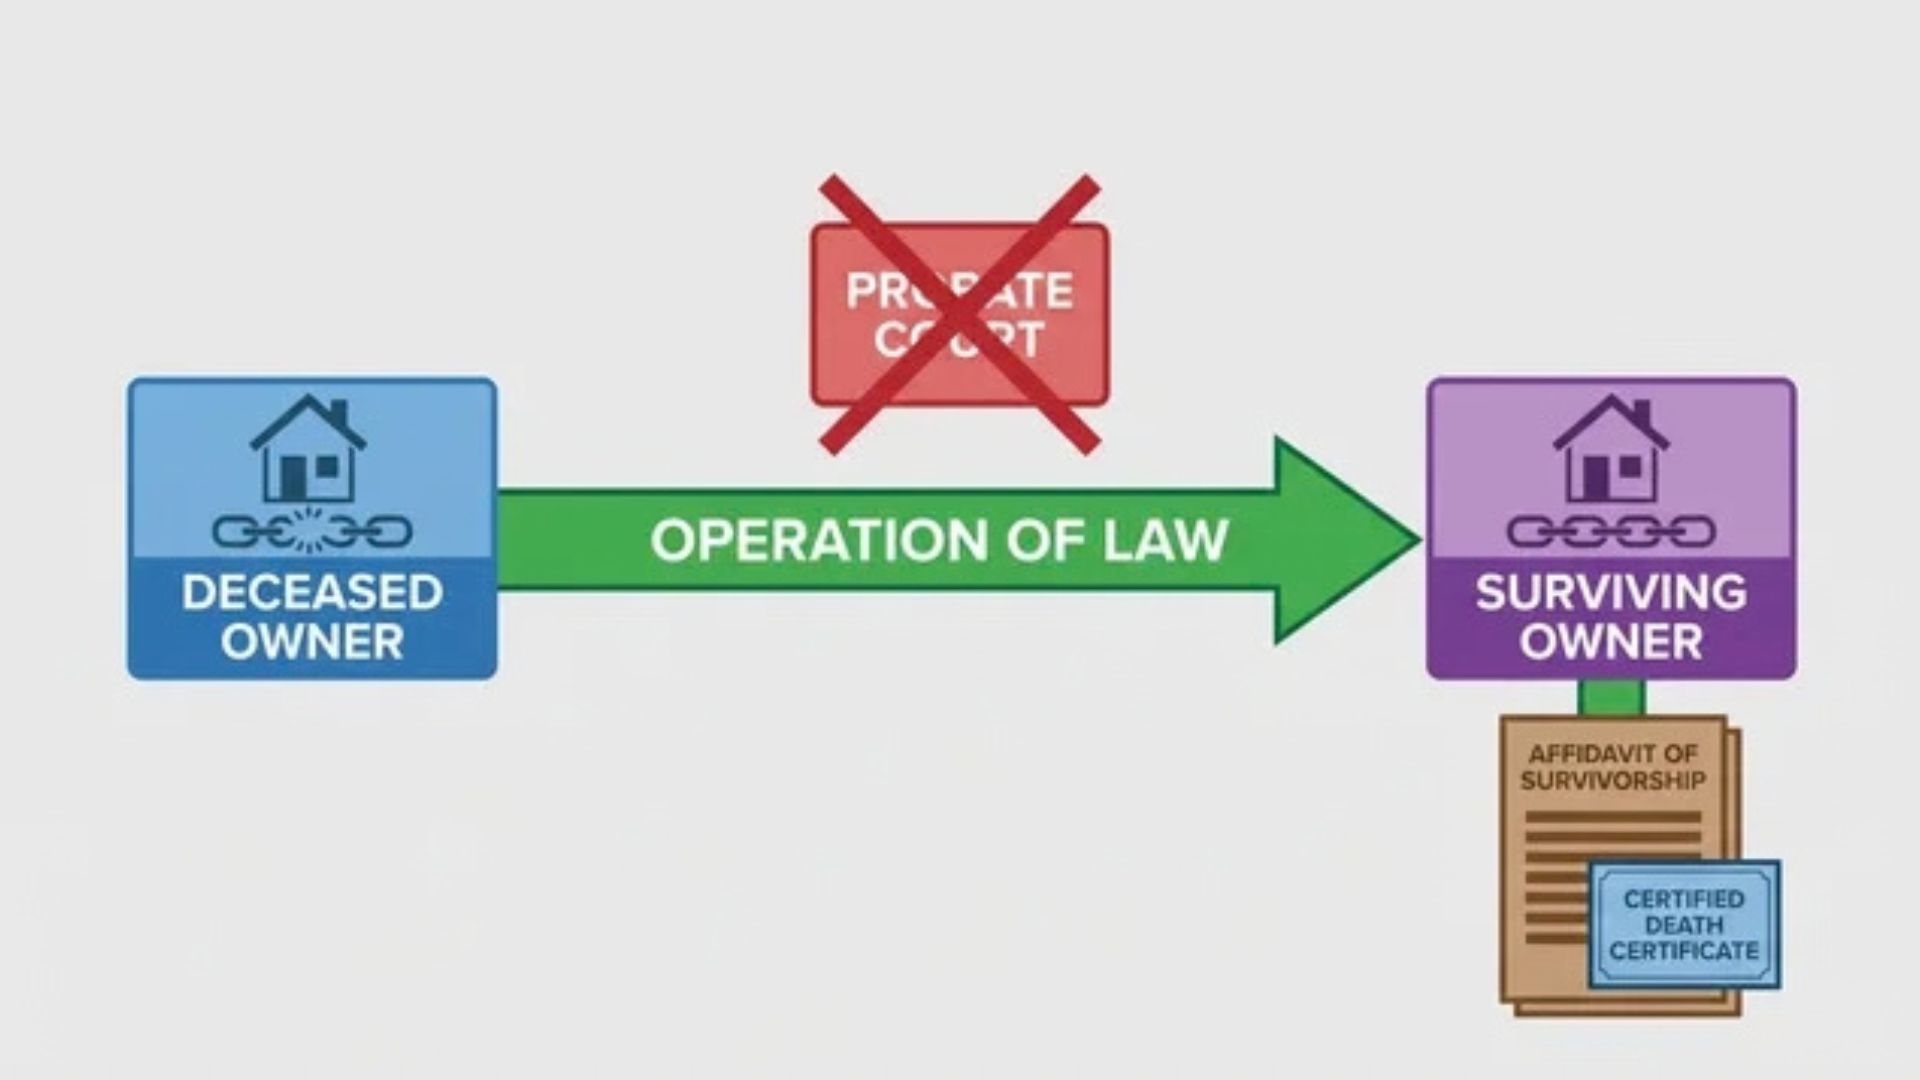
Survivorship transfers happen automatically by law. No will controls it, and no probate court gets involved.
It’s also the source of most of the confusion around this type of ownership.
Why the Transfer Skips Probate
When one owner dies, title moves by operation of law, that’s a legal term for “the law does it, not a court, not an executor.”
The deceased owner’s interest doesn’t become part of their estate. It never touches a will, because a will only controls property the person actually owned at death.
At the moment of death, that share is already gone. It passed to the surviving owners instantly, before probate could even start.
So writing “my share of the house goes to my daughter” in a will does nothing here. You can’t will away something you no longer own.
This is the whole reason JTWROS gets used for probate avoidance. There’s nothing left in the estate to probate.
What the Surviving Owner Has to Do
The surviving owner still has to clear paperwork. It’s just not court paperwork.
For real estate, that usually means recording an affidavit of survivorship with the county recorder, along with a certified copy of the death certificate. Some states call this form an affidavit of death of joint tenant.
For bank or brokerage accounts, the institution typically asks for the certified death certificate and its own claim form. It then updates its records and removes the deceased owner’s name.
This is an administrative process, not a judicial one. No judge signs off, and no hearing gets scheduled.
It can take a few weeks depending on the registry or institution. But there’s no court calendar to wait on, which is the real time savings.
Setting Up JTWROS Correctly on a Deed or Account
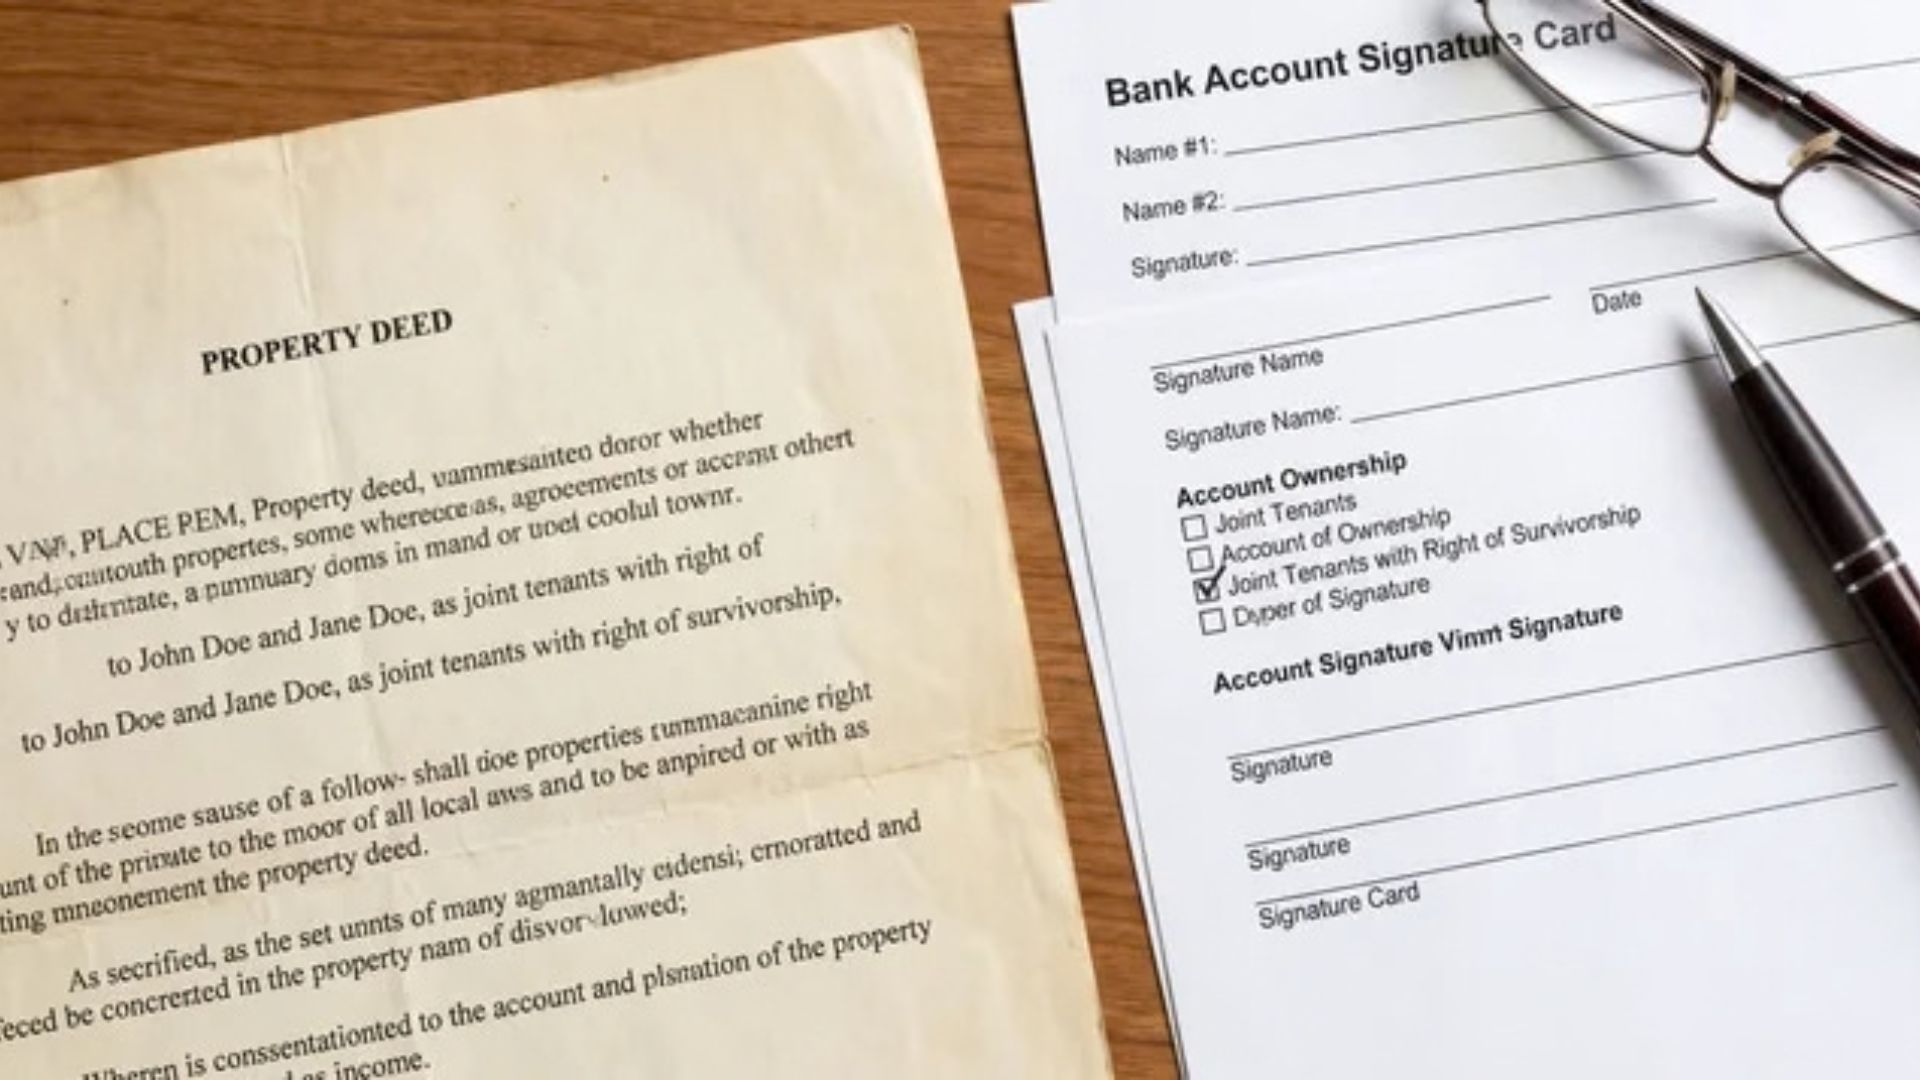
Survivorship rights don’t happen automatically just because two people own something together. The deed or account has to say so, in plain words.
Most states start with a different default: tenancy in common. That means if you co-own a house or a bank account and the paperwork doesn’t spell out survivorship, the law assumes each owner’s share passes to their heirs when they die, not to the other co-owner.
Why? Courts and title offices don’t guess at intent. Two people can own something together for all kinds of reasons, and wanting the other person to inherit automatically is a big assumption to make without being told. So the law waits for you to say it directly.
This is why you’ll see specific phrases like “joint tenants with right of survivorship” on deeds, brokerage account applications, bank signature cards, and even vehicle titles. Skip that language, and you’re probably in common by default.
One catch: the exact wording required isn’t the same everywhere. Some states want the full phrase, others accept abbreviations like “JTWROS.” Always check your state’s requirements before signing anything.
The Four Unities Behind a Valid Joint Tenancy
The right wording isn’t the only requirement. Traditional property law also looks for four “unities,” and a joint tenancy has to satisfy all of them. If one is missing, a court may treat the ownership as a tenancy in common.
- Unity of time: every owner gets their interest at the same moment.
- Unity of title: the interests come from the same deed or document for everyone.
- Unity of interest: shares are equal, so two owners each hold half and three owners each hold a third.
- Unity of possession: each owner has the right to use the entire property, not just part of it.
These four conditions also explain why severance works the way it does. If one of them breaks, for example when an owner sells their interest to someone new, the joint tenancy ends for that share.
Some states have relaxed the time and title rules. In those states, a person who already owns a property can create a joint tenancy by deeding it to themselves and someone else. Check your state’s rules before relying on that
Benefits of Choosing This Ownership Structure?
The biggest benefit of JTWROS is simple: property passes directly to the survivor without probate. Here’s what that actually gets you:
Speed: The surviving owner gets full control almost right away. There’s no waiting on a judge, no probate calendar, no months of legal back-and-forth. You just present a death certificate to the county recorder or the bank, and the transfer happens.
Cost savings: Probate isn’t cheap. You’re looking at court fees, attorney fees, and sometimes executor fees, all of which can eat into the estate’s value. JTWROS skips that process entirely for the asset in question, so more of it stays with the survivor.
Simplicity: Setting this up isn’t complicated. Real estate deeds, bank accounts, and brokerage accounts all let you add the right survivorship language when you open or retitle them. No trust, no complex estate planning documents, just the correct wording on the paperwork.
For couples and families who want a straightforward transfer, that combination is hard to beat.
Risks and Drawbacks to Weigh First
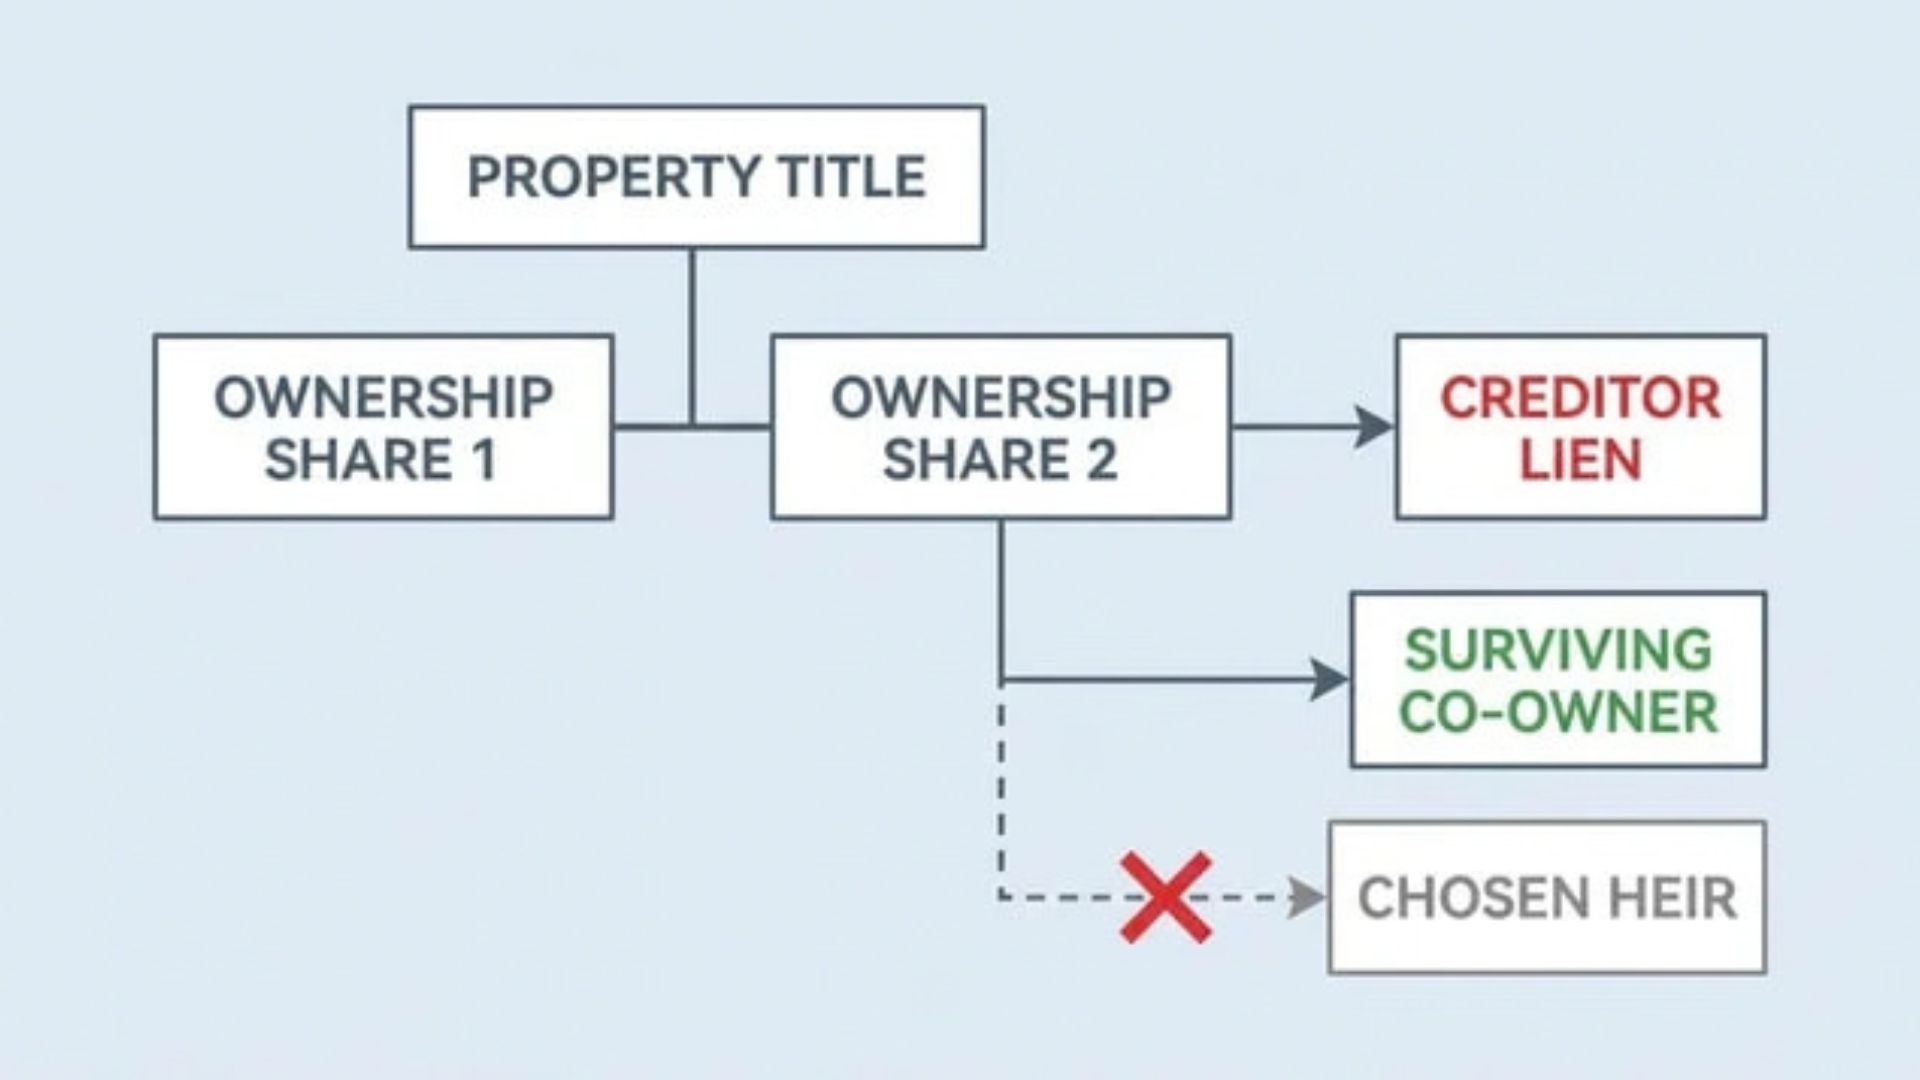
JTWROS limits what each owner can independently do with their share, both while they’re alive and after they die. You’re not fully in control, even though your name is on the title.
Loss of Control Over Your Share
You can’t leave your share to your kids, a spouse from a different marriage, or anyone else in your will. It doesn’t matter what your will says. The moment you die, your interest moves to the other joint tenants automatically.
This gets tricky if you have children from a prior relationship or specific people you want to inherit your portion. Under JTWROS, that’s just not possible unless you change the ownership structure first.
There’s also a longer-term issue. Whoever survives the longest ends up owning the whole asset outright. At that point, they decide where it goes next, and the other original owners’ wishes don’t factor in at all.
Exposure to a Co-Owner’s Creditors or Debts
Your co-owner’s financial problems can become your problem too. If a joint tenant gets sued and loses, or falls behind on debts, a creditor can go after that person’s share of the property.
In many states, this means the creditor can get a judgment lien placed on the debtor’s interest, or in some cases, force what’s called a partition sale of the whole property to collect what’s owed.
If you’re the innocent co-owner in this situation, your options are limited. You can try to negotiate a buyout, paying the creditor or the co-owner to remove the threat to the property.
Or you can file your own partition action, asking a court to divide or sell the property so you can separate your interest from the debt exposure. Neither option is quick or cheap, which is exactly why it’s worth thinking through before you add someone to a title.
How a Joint Tenancy Can Be Severed or Ended
A joint tenant can end their own survivorship rights unilaterally, without asking the other owners for permission, and this severance converts the ownership into a tenancy in common.
This can happen voluntarily, where an owner deeds their interest away, sometimes even transferring it to themselves through a new deed, just to break the legal “unity” that joint tenancy requires.
It can also happen involuntarily, when a court steps in through a partition action, usually because the owners can’t agree on what to do with the property. Once severance happens, survivorship disappears for that owner’s share.
Their portion now passes through their own estate plan or will instead of going automatically to the other co-owners. You don’t need anyone else’s sign-off to sever your own interest this way.
But if the severance leads to a dispute over dividing or selling the property itself, and the owners can’t work it out on their own, that’s when a court usually needs to get involved to sort out how the property gets split or sold.
JTWROS vs. Other Ownership: Comparison Chart
JTWROS is one of several ways to structure shared ownership, each trading off control, flexibility, and probate avoidance differently.
| Structure | Definition | Survivorship | Creditor Protection | Control Over Distribution | Setup Effort |
| JTWROS | Co-owners hold equal shares; a deceased owner’s share passes automatically to the survivor(s) | Yes, automatic | Low | Low (goes to survivor) | Low |
| Tenancy in Common | Co-owners can hold unequal shares, with no automatic transfer at death | No | Low | High (own will controls) | Low |
| Tenancy by the Entirety | A joint ownership form for married couples, available only in certain states, that treats the couple as one legal owner | Yes, automatic | High (spouses only) | Low | Low |
| Living Trust | A legal arrangement where a trustee holds assets for the owner and distributes them according to the trust’s terms | No (the trustee distributes, and probate is still avoided) | Low for a revocable trust; higher only with certain irrevocable trusts | High | High |
The right fit depends on whether you value speed and simplicity or more control over where your share ends up.
Tax Considerations for Joint Tenants
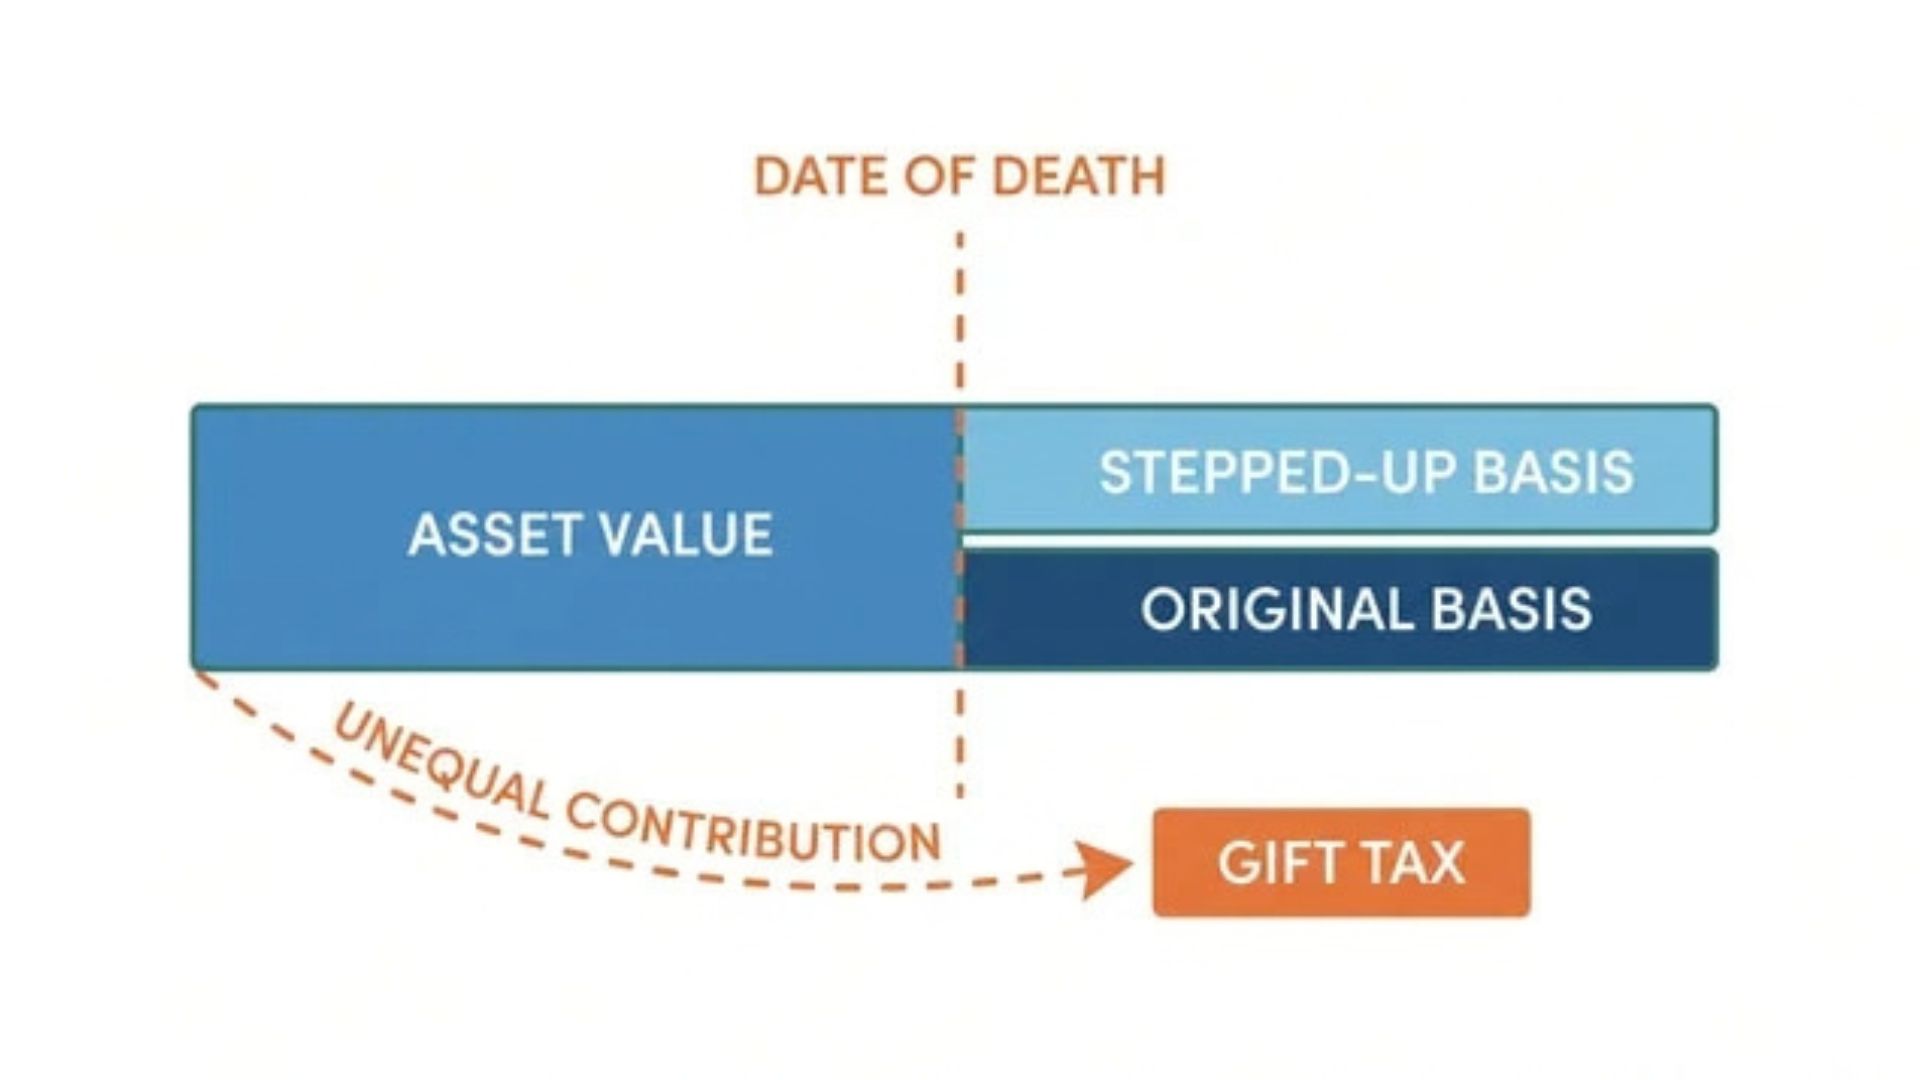
Adding a joint tenant or losing one can trigger gift tax or basis consequences that are easy to overlook.
Step-Up in Basis at Death
When a joint tenant dies, the portion of the asset counted in their estate gets a new basis equal to its fair market value on the date of death. How much of the asset gets that step-up depends on who the owners are.
For married couples, federal law (Internal Revenue Code Section 2040) generally counts exactly half the property in the deceased spouse’s estate, no matter who paid for it. Only that half steps up. The surviving spouse’s half keeps its original basis.
For non-spouse co-owners, like a parent and an adult child, the IRS looks at who actually paid. If the parent paid for everything, the full value can be counted in the parent’s estate, and the whole asset may get a stepped-up basis. Any portion the child paid for keeps its original basis.
In community property states, married couples who hold title as community property with right of survivorship keep the automatic transfer and can also get a full step-up in basis. Plain joint tenancy steps up only the deceased spouse’s share, which is why many couples there choose the community property option instead.
Gift Tax When Adding a Co-Owner
If your sibling or adult child didn’t pay for their share, the IRS generally treats their half of a jointly titled home as a gift, made the day you sign the new deed.
If that gift is worth more than the annual exclusion ($19,000 per recipient in 2026), you’ll need to file a gift tax return (Form 709). Actual tax is rare, because the amount counts against your lifetime exemption first.
Joint bank accounts work differently: the gift usually isn’t complete until the new owner withdraws money. Adding a spouse isn’t a taxable gift at all.
This often catches people off guard since it feels like paperwork, not a financial transfer. A tax professional can confirm whether your situation actually requires a filing.
Capital Gains on a Later Sale
Capital gains down the line depend directly on that basis. If the surviving owner sells the property later, their gain gets calculated using whatever basis they ended up with, which is why the step-up rules matter so much.
Say a married couple bought a home for $300,000, and it’s worth $700,000 when one spouse dies. The surviving spouse’s new basis is $500,000: their own $150,000 half plus the deceased spouse’s half, stepped up to $350,000. If they sell for $700,000, the taxable gain is $200,000 before any home-sale exclusion. Without the step-up, it would have been $400,000.
None of this is something to guess at. A tax professional who knows your state and your numbers can tell you exactly where you stand.
Choosing the Right Ownership Structure for Your Situation
The right ownership structure depends on how much control and flexibility you’re willing to give up for simplicity.
- JTWROS trade-off: it’s fast and easy to set up, but inflexible. You can’t will your share elsewhere, and you’re exposed to a co-owner’s creditors and debts.
- Spouses: often lean toward JTWROS or tenancy by the entirety, since the relationship and shared goals usually make the inflexibility less of a concern.
- Business partners or extended family: may prefer more control, especially if interests are unequal or estate plans differ, making tenancy in common or a trust worth a closer look.
- Before retitling anything: talk to an estate planning attorney or tax professional who can walk through your specific situation and state rules.
Final Takeaway
A joint tenant with rights of survivorship owns the whole property alongside everyone else on the title. That shared ownership is what lets a share pass straight to the survivors without probate.
The same feature is also what limits you. Your will can’t redirect your share, a co-owner’s debts can reach the property, and adding someone to the title can carry tax consequences for both of you.
If speed and simplicity matter most, this structure does its job well. If you want more say over where your share ends up, tenancy in common or a living trust may fit better. A real estate or estate planning attorney can confirm which one suits your state and your family.
Found this helpful? Share it with someone who needs it, and drop your questions in the comments below so we can help.
Frequently Asked Questions
Can the right of survivorship be challenged in court?
Yes, but it’s harder than contesting a will. Heirs must prove the joint tenancy was invalid through undue influence, fraud, forgery, or lack of capacity. For bank accounts, they may argue a name was added only for convenience. States also bar a co-owner who intentionally caused the death from inheriting.
Does joint tenancy with rights of survivorship work the same way for married couples?
Mostly. The transfer at death works the same for any co-owners. The differences are elsewhere: spouses get a step-up on only half the property, adding a spouse isn’t a taxable gift, and some states presume married co-owners hold title as tenants by the entirety instead.
What happens if a joint tenant sells their share without the other owners agreeing?
A joint tenant can usually sell their own share without consent, but not the whole property. The sale ends survivorship for that share, and the buyer becomes a tenant in common. Any other owners stay joint tenants with each other. If disputes follow, any owner can request a court partition.
Do I still owe estate tax on my share as the surviving owner?
Usually not directly. Federal estate tax falls on the deceased owner’s estate, which still counts jointly owned property even though it skips probate. Most estates sit far below the $15 million per-person exemption for 2026. In inheritance-tax states, the survivor may owe tax directly, though spouses are usually exempt.